 JamzNG Latest News, Gist, Entertainment in Nigeria
The federal government has defended its proposed $21.7 billion external borrowing plan, saying the funds will finance infrastructure and other productive investments that can expand the economy, create jobs and improve living standards.
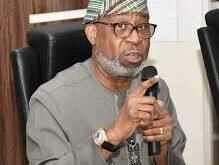
Finance Minister and Coordinating Minister for Economy, Taiwo Oyedele, said assets should judge the financing they would create and the expected economic returns, rather than judging it solely on its impact on Nigeria’s debt.
Responding to questions from State House correspondents after the Federal Executive Council (FEC) meeting chaired by President Bola Tinubu at the Presidential Villa, Abuja, Oyedele also said the administration is targeting single-digit inflation by the end of 2027 or earlier.
His defense followed former Vice President Atiku Abubakar’s call for the National Assembly to suspend approval until the government published full details of the projects, contracts, financing terms and repayment obligations.
NDC presidential candidate, Peter Obi, has separately warned of Nigeria’s debt service burden and its implications on spending on essential services.
Explaining the government’s position, Oyedele said the proposed facilities will support projects aimed at strengthening national productivity and generating lasting economic value.
“These are investments, not loans,” he said.
He said the financing package includes $20.52 billion and €1.045 billion for projects and programs in the fields of transport, security, health, agriculture, energy, digital infrastructure, education and social protection.
He said transportation accounts for about $10.6 billion, covering projects including the Sokoto-Badagry and Lagos-Calabar highways and the Kano-Kaduna railway line.
Oyedele said the government is seeking financing from multilateral and bilateral development partners, along with other sources, prioritizing favorable terms to keep costs low.
He said about $7.9 billion is expected from multilateral and bilateral partners, with the World Bank among the main institutions providing support.
According to the minister, a $5 billion component from the World Bank would attract concessional financing at an average interest rate of around 2.1%, while some social sector facilities would have rates of around 2%.
On the economy, Oyedele said inflation fell to 14.63% in September from 20.98% in the same period last year and from a peak of about 34%.
He said the FEC decided to step up efforts to reduce prices, particularly food prices, while supporting investments in infrastructure, human capital and job creation.
The minister said foreign reserves amounted to more than $55 billion, the highest in 18 years. Net reserves, he added, have risen above $45 billion from less than $1 billion three years ago.
It said economic growth stood at 4.43% in the second quarter, while the tax-to-GDP ratio increased from around 7% in 2023 to 12.5% by the end of 2025.
It said the debt service to revenue ratio also fell from 97% to less than 60%.
Defending the elimination of petrol subsidies, Oyedele said the previous agreement placed an unsustainable burden on public finances and limited investment in infrastructure and essential services.
He said the government had introduced interventions to cushion the effects of its reforms, including cash transfers, student finance and subsidized business loans.
It said more than 10 million families have received over ₦600 billion in cash transfers, while the Nigerian Education Loan Fund has disbursed ₦372.6 billion to more than 1.5 million students.
It said over 800,000 micro, small and medium enterprises have benefited from loans at single-digit interest rates.
It said workers earning up to ₦100,000 monthly are exempt from personal income tax, while businesses with an annual turnover of up to ₦100 million are entitled to exemption from corporate income tax, value added tax and withholding tax under relevant reforms.
The minister estimated the size of Nigeria’s capital market at over ₦160 trillion, up from around ₦30 trillion, and expressed optimism about the naira’s prospects, citing stronger reserves and improving economic fundamentals.
He said the government will continue to evaluate the effects of its policies and make necessary changes, with the ultimate goal of translating economic gains and public investments into better living conditions.